


ARTICLE CONTENTSOn this page 7 sections
Savings
Performance Objectives
By the end of the lesson, students should be able to:
- explain the meaning of savings;
- discuss the different types of savings;
- state and explain the components of savings;
- discuss the determinants of savings;
- explain the importance of savings.
Meaning of Savings
Savings refers to the part of income that is not spent on current consumption.
It is the money that an individual, household, business, or government sets aside for future use instead of spending it immediately. When people earn money, they typically use some of it to buy goods and services they need or want. The portion of their income that remains after all current expenses are paid is considered savings. This money can then be kept in a bank, invested, or stored in other ways.
Types of Savings
Savings can be broadly categorised into two main types: individual savings and national savings. These types reflect who is doing the saving and the scale of the savings.
Individual Savings
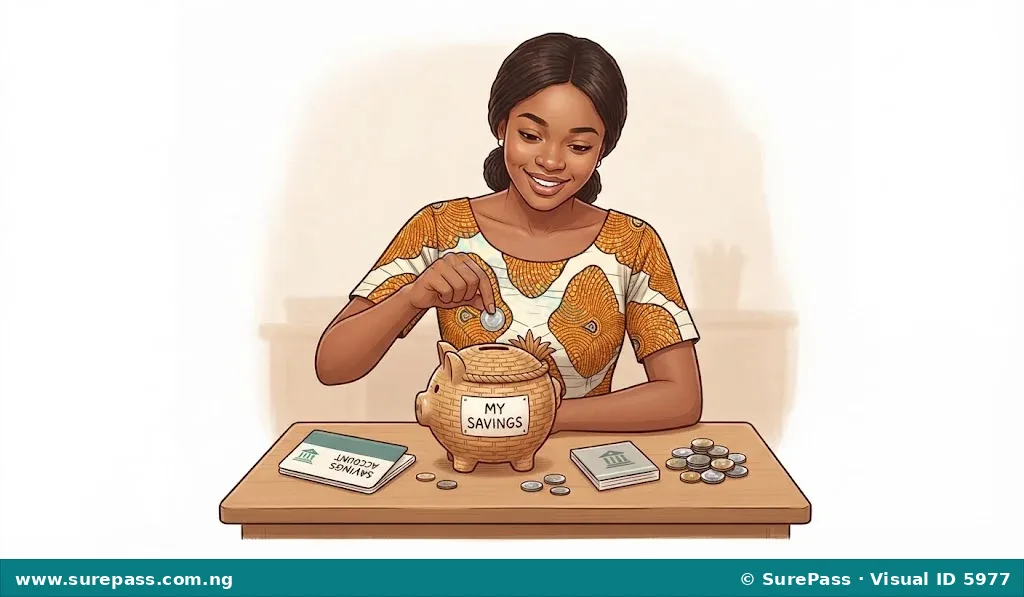
Individual savings refers to the portion of a person’s disposable income that is not spent on consumption but is set aside for future use.
This type of saving is done by individuals or households. People save for various personal reasons, such as buying a house, paying for education, retirement, or unexpected emergencies. Individual savings are often deposited in bank accounts, invested in shares, or kept in other financial instruments.
National Savings
National savings refers to the total amount of savings generated within an economy by all its sectors over a specific period.
It represents the sum of savings from individuals (households), businesses, and the government. National savings are crucial for a country’s economic growth because they provide the funds needed for investment in new factories, infrastructure, and technology. Higher national savings generally lead to higher investment and economic development.
Components of National Savings
National savings is made up of different parts contributed by the major sectors of an economy. The main components of national savings are:
-
Household Savings: This is the total savings made by individuals and families within the country. It is the largest component of national savings in many economies. Households save by depositing money in banks, investing in stocks and bonds, or contributing to pension funds.
-
Business Savings: This refers to the portion of a company’s profits that is not distributed to shareholders as dividends but is retained by the business for reinvestment or to cover future expenses. Businesses save to expand their operations, purchase new equipment, or improve technology.
-
Government Savings: This occurs when a government’s revenue (from taxes and other sources) is greater than its current expenditure. When the government spends less than it collects, the surplus contributes to national savings. Conversely, if government expenditure exceeds revenue, it results in a budget deficit, which reduces national savings.
Determinants of Savings
Several factors influence the level of savings by individuals and within an economy. These factors determine how much money people and institutions are willing and able to set aside for future use.
The key determinants of savings include:
-
Level of Income: This is one of the most significant determinants. Generally, as income increases, people have more disposable income, making it easier for them to save a larger portion. People with higher incomes tend to save more than those with lower incomes, who might spend most of their earnings on basic needs.
-
Interest Rates: The interest rate offered by financial institutions on savings can influence people’s decision to save. A higher interest rate means savers earn more money on their deposits, which can encourage them to save more. Conversely, lower interest rates might reduce the incentive to save.
-
Future Expectations: People’s expectations about their future income, prices, and economic conditions play a role. If individuals expect their income to fall in the future or anticipate higher prices (inflation), they might save more now to prepare. Similarly, if they expect a stable or rising income, they might save less.
-
Availability of Saving Facilities: The ease of access to banks, credit unions, and other financial institutions that offer saving products can affect saving habits. If there are many convenient and reliable places to save, people are more likely to do so. Lack of access to such facilities can discourage saving.
-
Cultural and Social Factors: The culture and social norms of a community can influence saving behaviour. Some cultures place a high value on thrift and saving for the future, while others might encourage more immediate consumption. Family traditions and peer influence can also play a role.
-
Government Policies: Government policies, such as tax incentives for saving (e.g., tax-free savings accounts) or mandatory pension contributions, can significantly impact national and individual savings rates. Policies that encourage responsible financial planning tend to boost savings.
Importance of Savings
Savings are vital for individuals, businesses, and the overall economy. They provide security, enable investment, and contribute to long-term growth and stability.
The importance of savings can be seen in several ways:
-
Financial Security for Individuals: Savings provide a safety net for unexpected events like illness, job loss, or emergencies. They also help individuals achieve long-term financial goals such as buying a home, funding education, or preparing for retirement.
-
Capital Formation and Investment: National savings are a primary source of funds for investment. When individuals and businesses save, this money is often deposited in banks, which then lend it to businesses for investment in new projects, equipment, and infrastructure. This process, known as capital formation, is essential for economic growth.
-
Economic Growth and Development: Higher levels of national savings lead to increased investment, which in turn drives economic growth. Investment in productive assets like factories, roads, and technology creates jobs, increases productivity, and improves living standards.
-
Reduced Reliance on Foreign Borrowing: Countries with high national savings can finance their investments domestically, reducing their need to borrow from foreign countries. This helps maintain economic independence and stability.
-
Inflation Control: When people save more, they spend less on current consumption. This can help to reduce aggregate demand in the economy, which can be a tool to control inflation, especially when there is too much money chasing too few goods.
-
Improved Standard of Living: Over time, consistent saving and investment lead to a stronger economy and greater wealth. This can result in better public services, more opportunities, and an overall higher standard of living for the population.
Inculcating the Culture of Saving
Developing a habit of saving is a valuable skill that provides long-term financial benefits. It involves making conscious decisions to set aside money regularly, regardless of income level.
How to Cultivate a Saving Habit
Inculcating a culture of saving requires discipline and a clear understanding of financial goals. The following steps can help individuals develop and maintain a saving habit:
-
Set Clear Financial Goals: Define what you are saving for. Whether it is for school fees, a new business, an emergency fund, or a future purchase, having specific goals makes saving more purposeful and motivating. Write down your goals and the amount of money needed for each.
-
Create a Budget: A budget helps you track your income and expenses. By knowing where your money goes, you can identify areas where you can cut down on spending and allocate more funds towards savings. List all your sources of income and all your regular expenses.
-
Save Regularly: Make saving a consistent habit. It is often recommended to save a fixed percentage of your income each time you receive it, even if it is a small amount. Treat savings as a non-negotiable expense, just like rent or food.
-
Open a Savings Account: Keep your savings separate from your spending money. Opening a dedicated savings account at a bank or a cooperative society can help you avoid dipping into your savings for everyday expenses. Some accounts offer higher interest rates, which can help your money grow.
-
Reduce Unnecessary Spending: Review your expenses and identify items that are not essential. Cutting down on luxury items, eating out less frequently, or finding cheaper alternatives for services can free up more money for savings.
-
Avoid Debt: High-interest debt, such as credit card debt, can make it difficult to save. Prioritise paying off debts to free up more of your income for savings. If you must borrow, ensure it is for productive purposes and that you can repay it promptly.
-
Review and Adjust: Regularly review your budget and savings progress. If your income or expenses change, adjust your saving plan accordingly. Celebrate small milestones to stay motivated and committed to your saving goals.
0 comments
Open the discussion when you need it. Comments stay collapsed until requested so the initial article remains light.