


ARTICLE CONTENTSOn this page 10 sections
Partnership Account
Performance Objectives
By the end of the lesson, students should be able to:
- state the meaning of partnership;
- explain the contents of a partnership agreement;
- distinguish between general and limited partnership;
- discuss the treatment of admission of new members;
- prepare partners’ capital and current accounts;
- prepare final accounts of partnerships;
- prepare a revaluation account.
Meaning of Partnership
A partnership is a type of business organisation where two or more people agree to carry on a business together, sharing its profits and losses.
Partnerships are common for professionals such as accountants, lawyers, and doctors, but they can also be found in other types of businesses. The partners contribute capital, skills, and labour to the business.
Partnership Deed or Agreement
A partnership deed, also known as a partnership agreement, is a written legal document that outlines the rights, duties, and responsibilities of each partner in a partnership business.
While a partnership can be formed orally, a written partnership deed is highly recommended to prevent disputes among partners. It serves as a blueprint for how the partnership will operate.
Contents of a Partnership Agreement
A comprehensive partnership agreement typically includes the following details:
- Name and Nature of the Business: The official name of the partnership and the type of business it will conduct.
- Names and Addresses of Partners: Full details of all individuals who are partners in the firm.
- Commencement Date: The date from which the partnership officially begins its operations.
- Duration of Partnership: Whether the partnership is for a fixed period or for a specific project, or if it is at will (meaning it can be dissolved by any partner at any time).
- Capital Contribution: The amount of capital (money or assets) each partner will contribute to the business.
- Profit and Loss Sharing Ratio: The agreed-upon proportion in which profits will be shared and losses will be borne by each partner. This is crucial for financial distribution.
- Interest on Capital: Whether partners will be allowed to earn interest on their capital contributions, and if so, the agreed rate.
- Interest on Drawings: Whether partners will be charged interest on money or goods they withdraw from the business for personal use, and the agreed rate.
- Partners’ Salaries: If any partner is to receive a salary for their active involvement in the business, the amount and frequency of payment.
- Partners’ Loans: Rules regarding loans made by partners to the firm, including interest rates and repayment terms.
- Drawings: The maximum amount each partner is allowed to withdraw from the business for personal use within a specific period.
- Procedure for Admission of New Partners: The conditions and process for bringing new members into the partnership.
- Procedure for Retirement or Death of a Partner: How the partnership will handle a partner leaving the firm or passing away, including valuation of their share.
- Procedure for Dissolution of Partnership: The steps to be followed if the partnership needs to be wound up.
- Arbitration Clause: A clause specifying how disputes among partners will be resolved, often through arbitration rather than court.
The importance of a partnership agreement lies in its ability to provide clarity, prevent misunderstandings, and offer a framework for resolving conflicts, thereby ensuring the smooth operation and stability of the business.
Types of Partnership
Partnerships can be classified into different types based on the liability of the partners.
General Partnership
A general partnership is a type of partnership where all partners have unlimited liability for the debts and obligations of the business.
This means that if the business cannot pay its debts, creditors can claim the personal assets of the partners to settle the outstanding amounts. All partners in a general partnership typically participate in the management of the business.
Limited Partnership
A limited partnership is a type of partnership that includes at least one general partner and one or more limited partners.
In a limited partnership, the general partner(s) have unlimited liability and manage the business, while the limited partner(s) have liability restricted to the amount of capital they have invested in the business. Limited partners usually do not participate in the day-to-day management of the firm.
The key distinction between general and limited partnerships is the extent of liability and involvement in management.
Types of Partners
Partners can also be categorised based on their involvement in the business and their liability.
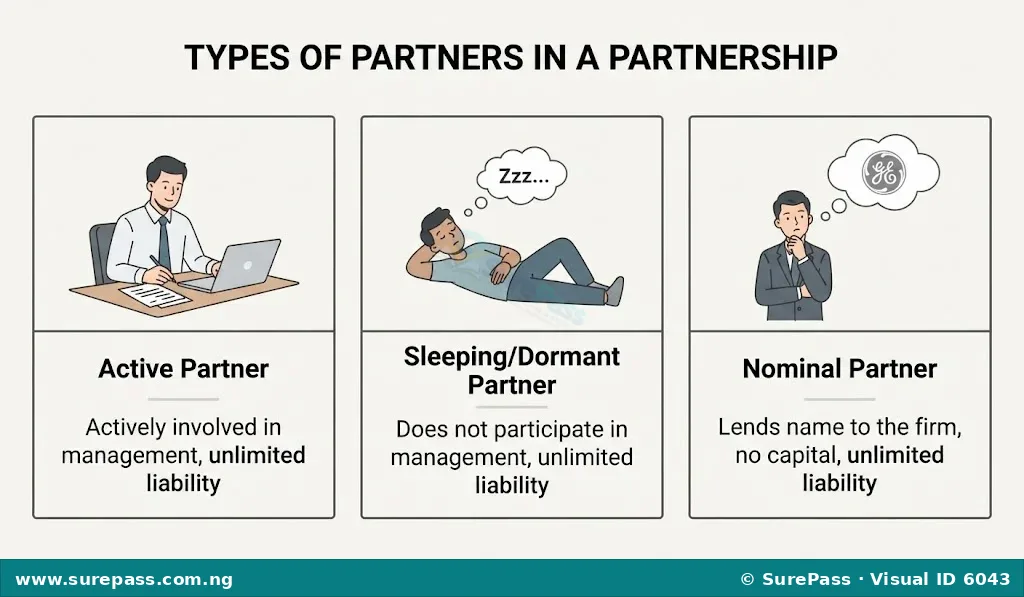
Active Partner
An active partner is a partner who actively participates in the day-to-day management and operations of the partnership business.
Active partners contribute capital, share in profits and losses, and have unlimited liability for the firm’s debts. They are involved in decision-making and represent the firm.
Sleeping/Dormant Partner
A sleeping or dormant partner is a partner who contributes capital and shares in the profits and losses of the business but does not take an active part in its management.
Despite their lack of involvement in management, sleeping partners still have unlimited liability for the firm’s debts, just like active partners. Their existence is usually known to the public.
Nominal Partner
A nominal partner is a person who lends their name to the partnership firm but does not contribute capital, participate in management, or share in the profits and losses.
Despite not being a ‘true’ partner in terms of capital or profit sharing, a nominal partner is still liable to third parties for the firm’s debts, as if they were a full partner. This is because their name gives credibility to the firm.
Treatment of Admission of New Members
The admission of a new partner into an existing partnership requires the consent of all existing partners, unless the partnership agreement states otherwise.
When a new partner is admitted, several adjustments need to be made in the partnership accounts to reflect the changes in ownership and financial structure. These adjustments ensure fairness to both the old and new partners.
Key Adjustments on Admission of a New Partner
The main adjustments typically include:
- Revaluation of Assets and Liabilities: Before a new partner joins, the assets and liabilities of the firm are often revalued to their current market values. This is done to ensure that the new partner does not benefit from any undisclosed profits or suffer from undisclosed losses that existed before their admission. Any profit or loss on revaluation is shared among the old partners in their old profit-sharing ratio.
- Goodwill Adjustment: Goodwill, which represents the reputation and earning capacity of the firm, may be valued upon the admission of a new partner. The new partner may be required to bring in a share of goodwill, or goodwill may be raised in the books and then written off, or adjusted through capital accounts. This compensates the old partners for the share of future profits that the new partner will receive due to the firm’s established reputation.
- Capital Contribution by New Partner: The new partner typically brings in capital, either in cash or in assets, according to the terms of the partnership agreement. This capital increases the total capital of the firm.
- Adjustment of Capital Accounts: The capital accounts of the old partners may need to be adjusted to reflect the revaluation profit/loss and goodwill adjustments. Sometimes, partners may agree to adjust their capital accounts to a new agreed ratio after the admission of the new partner.
- New Profit-Sharing Ratio: A new profit-sharing ratio is agreed upon by all partners (old and new) for future profits and losses.
These adjustments are crucial for maintaining equity among partners and accurately reflecting the financial position of the partnership after the admission of a new member.
Preparing Partners’ Capital and Current Accounts
Partners’ capital and current accounts are essential for recording the financial transactions between the partners and the partnership firm.
There are two main methods for maintaining partners’ capital accounts: the Fixed Capital Method and the Fluctuating Capital Method.
Fixed Capital Method
Under the fixed capital method, partners’ capital accounts remain constant unless additional capital is introduced or capital is permanently withdrawn.
All transactions related to drawings, interest on capital, interest on drawings, salaries, and share of profit or loss are recorded in a separate account called the Partners’ Current Account.
Partners’ Capital Account (Fixed Method)
This account shows the initial capital contributed and any permanent additions or withdrawals.
The format for a Partners’ Capital Account is:
| Partners’ Capital Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Partner A (₦) | Partner B (₦) | Date | Particulars | Partner A (₦) | Partner B (₦) |
| To Bank (Permanent Withdrawal) | X | X | By Bank (Initial Capital) | X | X | ||
| To Balance c/d | X | X | By Bank (Additional Capital) | X | X | ||
| XXX | XXX | XXX | XXX | ||||
Partners’ Current Account (Fixed Method)
This account records all other transactions affecting partners’ equity, such as drawings, interest on drawings, interest on capital, salaries, and share of profit or loss.
The format for a Partners’ Current Account is:
| Partners’ Current Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Partner A (₦) | Partner B (₦) | Date | Particulars | Partner A (₦) | Partner B (₦) |
| To Drawings | X | X | By Balance b/d (Cr) | X | X | ||
| To Interest on Drawings | X | X | By Interest on Capital | X | X | ||
| To Profit & Loss Appropriation (Loss) | X | X | By Salary | X | X | ||
| To Balance c/d (Cr) | X | X | By Profit & Loss Appropriation (Profit) | X | X | ||
| To Balance c/d (Dr) | X | X | By Balance b/d (Dr) | X | X | ||
| XXX | XXX | XXX | XXX | ||||
Fluctuating Capital Method
Under the fluctuating capital method, only one account, the Partners’ Capital Account, is maintained for each partner.
All transactions, including capital contributions, drawings, interest on capital, interest on drawings, salaries, and share of profit or loss, are recorded directly in this single capital account. As a result, the balance of the capital account fluctuates from period to period.
Partners’ Capital Account (Fluctuating Method)
The format for a Partners’ Capital Account under the fluctuating method is:
| Partners’ Capital Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Partner A (₦) | Partner B (₦) | Date | Particulars | Partner A (₦) | Partner B (₦) |
| To Drawings | X | X | By Balance b/d | X | X | ||
| To Interest on Drawings | X | X | By Bank (Additional Capital) | X | X | ||
| To Profit & Loss Appropriation (Loss) | X | X | By Interest on Capital | X | X | ||
| To Balance c/d | X | X | By Salary | X | X | ||
| By Profit & Loss Appropriation (Profit) | X | X | |||||
| XXX | XXX | XXX | XXX | ||||
Worked Example: Partners’ Capital and Current Accounts
Ayo and Bola are partners sharing profits and losses in the ratio 3:2. Their capital contributions as at 1st January 2023 were Ayo ₦100,000 and Bola ₦80,000. The partnership agreement provides for:
- Interest on capital at 5% per annum.
- Interest on drawings at 10% per annum.
- Ayo to receive a salary of ₦12,000 per annum.
During the year, Ayo drew ₦15,000 and Bola drew ₦10,000. Interest on drawings for Ayo was ₦750 and for Bola was ₦500. The net profit for the year ended 31st December 2023 was ₦60,000.
Prepare the Partners’ Capital and Current Accounts using both Fixed and Fluctuating Capital Methods.
Solution (Fixed Capital Method)
Step 1: Calculate Interest on Capital
- Ayo: 5% of ₦100,000 = ₦5,000
- Bola: 5% of ₦80,000 = ₦4,000
Step 2: Prepare Profit and Loss Appropriation Account (to determine distributable profit)
| Profit and Loss Appropriation Account for the year ended 31st December 2023 | |
|---|---|
| Net Profit | ₦60,000 |
| Add: Interest on Drawings: | |
| Ayo | ₦750 |
| Bola | ₦500 |
| ₦1,250 | |
| ₦61,250 | |
| Less: Interest on Capital: | |
| Ayo | ₦5,000 |
| Bola | ₦4,000 |
| (₦9,000) | |
| Less: Partners’ Salary: | |
| Ayo | (₦12,000) |
| Distributable Profit | ₦40,250 |
Step 3: Distribute Profit
Profit-sharing ratio 3:2 (Total 5 parts)
- Ayo’s share: (3/5) * ₦40,250 = ₦24,150
- Bola’s share: (2/5) * ₦40,250 = ₦16,100
Step 4: Prepare Partners’ Capital Accounts (Fixed)
| Partners’ Capital Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Ayo (₦) | Bola (₦) | Date | Particulars | Ayo (₦) | Bola (₦) |
| Dec 31, 2023 | To Balance c/d | 100,000 | 80,000 | Jan 1, 2023 | By Balance b/d | 100,000 | 80,000 |
| 100,000 | 80,000 | 100,000 | 80,000 | ||||
Step 5: Prepare Partners’ Current Accounts (Fixed)
| Partners’ Current Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Ayo (₦) | Bola (₦) | Date | Particulars | Ayo (₦) | Bola (₦) |
| Dec 31, 2023 | To Drawings | 15,000 | 10,000 | Dec 31, 2023 | By Interest on Capital | 5,000 | 4,000 |
| Dec 31, 2023 | To Interest on Drawings | 750 | 500 | Dec 31, 2023 | By Salary | 12,000 | – |
| Dec 31, 2023 | To Balance c/d | 25,400 | 9,600 | Dec 31, 2023 | By Profit & Loss App. (Profit) | 24,150 | 16,100 |
| 41,150 | 20,100 | 41,150 | 20,100 | ||||
Solution (Fluctuating Capital Method)
Step 1, 2, 3: (Same as Fixed Capital Method)
Step 4: Prepare Partners’ Capital Accounts (Fluctuating)
| Partners’ Capital Account | |||||||
|---|---|---|---|---|---|---|---|
| Date | Particulars | Ayo (₦) | Bola (₦) | Date | Particulars | Ayo (₦) | Bola (₦) |
| Dec 31, 2023 | To Drawings | 15,000 | 10,000 | Jan 1, 2023 | By Balance b/d | 100,000 | 80,000 |
| Dec 31, 2023 | To Interest on Drawings | 750 | 500 | Dec 31, 2023 | By Interest on Capital | 5,000 | 4,000 |
| Dec 31, 2023 | To Balance c/d | 125,400 | 89,600 | Dec 31, 2023 | By Salary | 12,000 | – |
| Dec 31, 2023 | By Profit & Loss App. (Profit) | 24,150 | 16,100 | ||||
| 141,150 | 100,100 | 141,150 | 100,100 | ||||
Preparing Final Accounts of Partnerships
The final accounts of a partnership are similar to those of a sole proprietorship, but with an additional account called the Profit and Loss Appropriation Account.
The final accounts typically include:
- Trading Account: To determine the Gross Profit or Gross Loss.
- Profit and Loss Account: To determine the Net Profit or Net Loss before appropriation.
- Profit and Loss Appropriation Account: To show how the net profit is distributed among partners.
- Balance Sheet: To show the financial position of the partnership at a specific date.
Profit and Loss Appropriation Account
This account is unique to partnerships and shows how the net profit (or loss) for the period is distributed among the partners according to the partnership agreement.
It includes items such as interest on capital, partners’ salaries, interest on drawings, and the final share of profit or loss.
Format of Profit and Loss Appropriation Account
| Profit and Loss Appropriation Account for the year ended … | |
|---|---|
| Net Profit (from Profit & Loss Account) | ₦X |
| Add: Interest on Drawings: | |
| Partner A | ₦X |
| Partner B | ₦X |
| ₦X | |
| ₦X | |
| Less: Interest on Capital: | |
| Partner A | ₦X |
| Partner B | ₦X |
| (₦X) | |
| Less: Partners’ Salaries: | |
| Partner A | (₦X) |
| Partner B | (₦X) |
| Distributable Profit | ₦X |
| Share of Profit: | |
| Partner A | ₦X |
| Partner B | ₦X |
| ₦X | |
Worked Example: Final Accounts of a Partnership
Using the information from the previous example for Ayo and Bola, and assuming the following additional details from their trial balance:
Sales: ₦500,000
Cost of Goods Sold: ₦300,000
Operating Expenses (excluding partners’ salaries): ₦140,000
Prepare the Trading, Profit & Loss, and Profit & Loss Appropriation Accounts for the year ended 31st December 2023.
Solution
1. Trading Account
| Trading Account for the year ended 31st December 2023 | |
|---|---|
| Sales | ₦500,000 |
| Less: Cost of Goods Sold | (₦300,000) |
| Gross Profit | ₦200,000 |
2. Profit and Loss Account
| Profit and Loss Account for the year ended 31st December 2023 | |
|---|---|
| Gross Profit b/d | ₦200,000 |
| Less: Operating Expenses | (₦140,000) |
| Net Profit | ₦60,000 |
3. Profit and Loss Appropriation Account
(This is the same as calculated in the previous example)
| Profit and Loss Appropriation Account for the year ended 31st December 2023 | |
|---|---|
| Net Profit | ₦60,000 |
| Add: Interest on Drawings: | |
| Ayo | ₦750 |
| Bola | ₦500 |
| ₦1,250 | |
| ₦61,250 | |
| Less: Interest on Capital: | |
| Ayo | ₦5,000 |
| Bola | ₦4,000 |
| (₦9,000) | |
| Less: Partners’ Salary: | |
| Ayo | (₦12,000) |
| Distributable Profit | ₦40,250 |
| Share of Profit: | |
| Ayo (3/5) | ₦24,150 |
| Bola (2/5) | ₦16,100 |
| ₦40,250 | |
Preparing a Revaluation Account
A revaluation account is prepared to record the increase or decrease in the value of assets and liabilities when there is a change in the profit-sharing ratio among existing partners, or more commonly, upon the admission or retirement of a partner.
The purpose of this account is to determine the true value of the firm’s assets and liabilities at the time of the change and to distribute any resulting profit or loss among the old partners in their old profit-sharing ratio.
Rules for Revaluation Account
- Increase in Asset Value: Credited to Revaluation Account.
- Decrease in Asset Value: Debited to Revaluation Account.
- Increase in Liability Value: Debited to Revaluation Account.
- Decrease in Liability Value: Credited to Revaluation Account.
- Unrecorded Assets: Credited to Revaluation Account.
- Unrecorded Liabilities: Debited to Revaluation Account.
The balance of the Revaluation Account (profit or loss) is then transferred to the old partners’ capital accounts in their old profit-sharing ratio.
Format of Revaluation Account
| Revaluation Account | |||
|---|---|---|---|
| Particulars | Amount (₦) | Particulars | Amount (₦) |
| To Asset (e.g., Machinery) (Decrease) | X | By Asset (e.g., Land) (Increase) | X |
| To Liability (e.g., Creditors) (Increase) | X | By Liability (e.g., Debtors) (Decrease) | X |
| To Unrecorded Liability | X | By Unrecorded Asset | X |
| To Partners’ Capital A/c (Profit on Revaluation) | X | By Partners’ Capital A/c (Loss on Revaluation) | X |
| XXX | XXX | ||
Worked Example: Revaluation Account
Femi and Grace are partners sharing profits and losses in the ratio 2:1. They admit Henry as a new partner. Before Henry’s admission, the following revaluations were agreed upon:
- Machinery to be depreciated by ₦5,000.
- Building to be appreciated by ₦10,000.
- Provision for doubtful debts to be increased by ₦1,000.
- Stock to be valued at ₦2,000 more than its book value.
- An unrecorded liability for repairs of ₦500 was discovered.
Prepare the Revaluation Account.
Solution
| Revaluation Account | |||
|---|---|---|---|
| Particulars | Amount (₦) | Particulars | Amount (₦) |
| To Machinery (Decrease) | 5,000 | By Building (Increase) | 10,000 |
| To Provision for Doubtful Debts (Increase) | 1,000 | By Stock (Increase) | 2,000 |
| To Unrecorded Liability (Repairs) | 500 | ||
| To Partners’ Capital A/c (Profit on Revaluation): | |||
| Femi (2/3) | 3,667 | ||
| Grace (1/3) | 1,833 | ||
| 5,500 | |||
| 12,000 | 12,000 | ||
Calculation of Profit on Revaluation:
Total Credits = ₦10,000 (Building) + ₦2,000 (Stock) = ₦12,000
Total Debits = ₦5,000 (Machinery) + ₦1,000 (Provision) + ₦500 (Unrecorded Liability) = ₦6,500
Profit on Revaluation = ₦12,000 – ₦6,500 = ₦5,500
Distribution of Profit (Femi:Grace = 2:1):
Femi’s share = (2/3) * ₦5,500 = ₦3,666.67 ≈ ₦3,667
Grace’s share = (1/3) * ₦5,500 = ₦1,833.33 ≈ ₦1,833
0 comments
Open the discussion when you need it. Comments stay collapsed until requested so the initial article remains light.