


ARTICLE CONTENTSOn this page 11 sections
Entrepreneurial Finance I
Performance Objectives
By the end of the lesson, students should be able to:
- state the meaning and importance of entrepreneurial finance;
- differentiate between personal finance and business finance;
- identify the sources of business finance;
- explain the meaning and importance of financial goals;
- prepare a simple business plan following identified steps;
- create a monthly budget for a small business idea.
Meaning of Entrepreneurial Finance
Entrepreneurial finance is the study of how entrepreneurs raise and manage money to start, operate, and grow their businesses.
It involves understanding where money comes from, how it is used, and how to make financial decisions that help a new business succeed. This type of finance focuses on the unique challenges and opportunities faced by new and growing ventures, which often have limited resources and higher risks compared to established companies.
Importance of Entrepreneurial Finance
Entrepreneurial finance is crucial for the survival and growth of any new business. Without proper financial management, even a brilliant business idea can fail.
The importance of entrepreneurial finance includes:
- Starting a Business: It provides the initial capital needed to set up operations, buy equipment, rent a space, and purchase initial inventory.
- Operating the Business: It ensures there is enough money to cover daily expenses such as salaries, utility bills, and raw materials.
- Growing the Business: It helps entrepreneurs find funds to expand their operations, introduce new products, or enter new markets.
- Making Informed Decisions: Understanding finance allows entrepreneurs to make smart choices about pricing, investments, and spending, which affects the profitability of the business.
- Managing Risks: It helps in planning for unexpected financial challenges and ensures the business has a buffer to handle difficult times.
- Attracting Investors: A clear understanding of finance and a well-managed financial plan can attract potential investors or lenders who are looking for viable businesses.
Differences Between Personal Finance and Business Finance
While both personal and business finance involve managing money, they have distinct characteristics and objectives. Understanding these differences is important for any entrepreneur.
Personal Finance
Personal finance refers to the management of an individual’s money and financial decisions, including income, expenses, savings, investments, and debt.
The main goal of personal finance is to meet individual or family financial goals, such as buying a home, saving for education, planning for retirement, or managing daily household expenses. Decisions are often based on personal needs, preferences, and risk tolerance.
Business Finance
Business finance is the management of money and financial decisions within a business entity, including raising capital, allocating funds, managing cash flow, and making investment decisions to achieve business objectives.
The primary goal of business finance is to maximise the value of the business for its owners, ensure its sustainability, and achieve its strategic objectives. Decisions are driven by profitability, growth potential, market conditions, and legal requirements.
Key Distinctions
The main differences between personal finance and business finance are:
- Purpose: Personal finance focuses on individual or household needs, while business finance focuses on the needs and goals of the business entity.
- Source of Funds: Personal funds come from salaries, wages, or personal investments. Business funds come from owners’ capital, loans, sales revenue, or investments.
- Decision-Making: Personal financial decisions are often emotional or based on individual preferences. Business financial decisions are typically analytical, strategic, and aimed at profit maximisation and growth.
- Legal Structure: Personal finance does not involve a separate legal entity. Business finance operates within a specific legal structure (e.g., sole proprietorship, partnership, company).
- Risk: Personal financial risk primarily affects the individual or family. Business financial risk affects the business, its owners, employees, and sometimes even the economy.
- Record Keeping: Personal finance record keeping can be informal. Business finance requires strict, formal, and often legally mandated accounting records and financial statements.
- Taxation: Personal income is taxed individually. Business profits are taxed at the business level, and owners may also pay personal income tax on their earnings from the business.
Sources of Business Finance
Every business, whether small or large, needs money to start and operate. These funds can come from various sources, each with its own advantages and disadvantages.
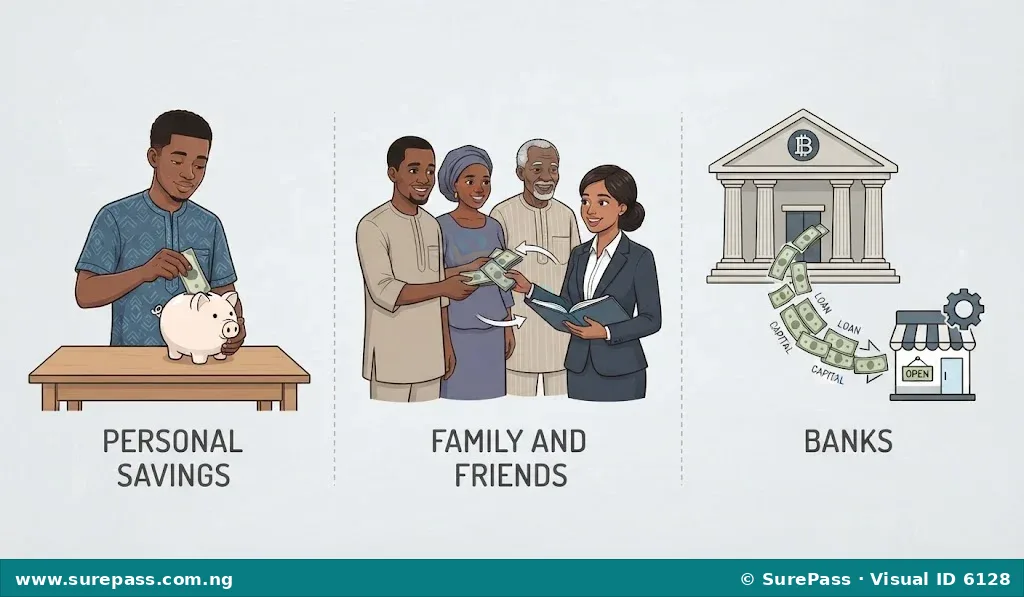
1. Personal Savings
Personal savings are funds that an entrepreneur has saved from their own income or other personal assets. This is often the first source of finance for many small businesses.
Using personal savings means the entrepreneur does not have to pay interest or give up ownership of their business to others. However, it can put the entrepreneur’s personal financial security at risk if the business fails.
2. Family and Friends
Funds borrowed or invested by family members and friends are a common source of startup capital for many entrepreneurs.
This source often comes with more flexible repayment terms and lower interest rates compared to traditional lenders. However, it is important to treat these arrangements formally with clear agreements to avoid damaging personal relationships if the business faces difficulties.
3. Banks and Financial Institutions
Banks and other financial institutions, such as microfinance banks, offer various types of loans and credit facilities to businesses.
These institutions provide structured financing options, but they usually require a solid business plan, collateral, and a good credit history. Examples of financial institutions include commercial banks like First Bank, Zenith Bank, and Access Bank, as well as development banks that support specific sectors.
Financial Goals and Planning
For any business to succeed, it needs clear financial direction. This direction comes from setting financial goals and creating a plan to achieve them.
Meaning of Financial Goals
Financial goals are specific, measurable objectives that a business aims to achieve regarding its money and financial resources over a defined period.
These goals can be short-term (e.g., increasing monthly sales by 10%), medium-term (e.g., purchasing new equipment within two years), or long-term (e.g., becoming the market leader in five years). They provide a target for the business’s financial efforts.
Importance of Financial Goals
Setting financial goals is vital for several reasons:
- Direction and Focus: Goals give the business a clear direction, helping entrepreneurs focus their efforts and resources on what truly matters.
- Motivation: Achieving financial milestones can motivate the entrepreneur and their team to work harder and smarter.
- Decision-Making: Goals serve as a benchmark for making financial decisions. Every decision can be evaluated against whether it helps achieve the set goals.
- Performance Measurement: They allow the business to track its progress and measure its financial performance over time.
- Resource Allocation: Goals help in allocating financial resources effectively, ensuring that money is spent on activities that contribute to achieving the objectives.
- Attracting Investment: Clear and realistic financial goals can make a business more attractive to potential investors or lenders.
Meaning of Financial Planning
Financial planning is the process of developing strategies to manage a business’s financial resources to achieve its financial goals.
It involves forecasting income and expenses, making investment decisions, managing cash flow, and planning for future growth. A good financial plan acts as a roadmap for the business’s financial journey.
Steps in Setting Financial Goals and Plan
Setting effective financial goals and creating a robust financial plan involves a structured approach.
The steps in setting financial goals and plan include:
- Define Your Business Vision: Clearly understand what the business aims to achieve in the long term. This vision will guide your financial goals.
- Set Specific and Measurable Goals: Financial goals should be clear, quantifiable, and have a deadline. For example, instead of “make more money,” set “increase monthly revenue by 15% within the next six months.”
- Assess Your Current Financial Situation: Understand where the business stands financially right now. This involves looking at current assets, liabilities, income, and expenses.
- Identify Financial Needs: Determine how much money is needed to achieve each goal and for what purpose (e.g., equipment, marketing, salaries).
- Develop Strategies to Achieve Goals: Outline the specific actions the business will take to reach its financial targets. This could include increasing sales, reducing costs, or seeking external funding.
- Create a Budget: Develop a detailed budget that allocates funds to different areas of the business, ensuring that expenses are controlled and resources are used efficiently.
- Monitor and Review: Regularly track financial performance against the goals and budget. Make adjustments to the plan as needed based on market changes or business performance.
- Seek Professional Advice (if needed): For complex financial matters, consulting with an accountant or financial advisor can provide valuable insights.
Business Budgeting
Budgeting is a fundamental aspect of financial planning for any business, especially for small and new ventures.
Meaning of Business Budgeting
Business budgeting is the process of creating a detailed financial plan that estimates a business’s expected income and expenses over a specific future period, usually a month, quarter, or year.
A budget acts as a financial roadmap, guiding how money will be earned and spent to achieve the business’s financial goals. It helps in allocating resources efficiently and controlling spending.
Importance of Business Budgeting
Business budgeting is important for several reasons:
- Financial Control: It helps the business keep track of its spending and ensures that expenses do not exceed income.
- Resource Allocation: A budget helps in deciding where to best use the business’s money, prioritising essential expenditures and investments.
- Performance Evaluation: It provides a benchmark against which actual financial performance can be measured, allowing the business to identify areas of overspending or underperformance.
- Decision-Making: Budgets provide valuable information for making informed decisions about pricing, production levels, and expansion plans.
- Cash Flow Management: By forecasting income and expenses, a budget helps in managing cash flow, ensuring the business has enough money to meet its obligations.
- Goal Achievement: It links financial activities directly to the business’s financial goals, making it easier to work towards achieving them.
Preparing a Simple Business Plan
A business plan is a formal document that outlines a business’s goals, strategies, and how it plans to achieve them. For SS1 learners, a simple business plan focuses on the core elements.
A simple business plan helps an entrepreneur organise their thoughts, identify potential challenges, and present their idea clearly to others, such as family, friends, or potential lenders.
Key Components of a Simple Business Plan
A simple business plan typically includes the following sections:
- Executive Summary: A brief overview of the entire business plan, including the business idea, its goals, and how it will succeed. It should be concise and compelling.
- Company Description: Details about the business, such as its name, what it does, its mission, and its legal structure (e.g., sole proprietorship).
- Products or Services: A clear description of what the business sells, including its features and benefits to customers.
- Market Analysis: Information about the target customers, the size of the market, and who the competitors are. It should explain how the business will stand out.
- Marketing and Sales Strategy: How the business will attract customers and sell its products or services. This includes pricing, promotion, and distribution methods.
- Management Team: Who is running the business and their relevant skills or experience. For a small business, this might just be the entrepreneur.
- Financial Plan: A summary of the business’s financial needs, projected income, expenses, and how it will make a profit. This section will include the budget.
Creating a Monthly Budget for a Small Business Idea
Creating a monthly budget is a practical skill that helps entrepreneurs manage their business finances effectively. This involves estimating all expected income and expenses for a month.
Steps to Create a Monthly Budget
The procedure involves the following steps:
- List All Expected Income: Identify all sources of money coming into the business for the month. This could include projected sales revenue, loans received, or owner contributions.
Example: If you plan to sell 50 loaves of bread at N800 each, your projected sales income is N40,000.
- List All Expected Expenses: Identify all costs the business expects to incur during the month. Categorise these expenses to make them easier to track.
Examples of expenses include:
- Rent for shop space
- Raw materials (e.g., flour, sugar, yeast for baking)
- Utility bills (electricity, water)
- Salaries or wages (if any employees)
- Transportation costs
- Marketing and advertising
- Loan repayments
- Miscellaneous expenses
- Estimate Each Income and Expense Amount: Assign a realistic monetary value to each item on your income and expense lists. Use past records if available, or research typical costs for your industry.
Example: If flour costs N10,000, sugar N3,000, and yeast N1,000 for the month, total raw materials cost N14,000.
- Calculate Total Expected Income: Add up all the estimated income amounts.
- Calculate Total Expected Expenses: Add up all the estimated expense amounts.
- Determine Net Financial Position: Subtract total expected expenses from total expected income.
If Income > Expenses, the business has a projected surplus (profit).
If Expenses > Income, the business has a projected deficit (loss).
- Review and Adjust: If there is a projected deficit, look for ways to reduce expenses or increase income. If there is a surplus, consider how to reinvest it for growth or save it for future needs.
Example: Monthly Budget for a Small Bread-Making Business
Imagine a small business that bakes and sells bread. Here is a simple monthly budget:
Projected Income:
- Sales of bread (50 loaves x N800) = N40,000
- Total Expected Income = N40,000
Projected Expenses:
- Rent for small bakery space = N5,000
- Raw materials (flour, sugar, yeast, etc.) = N14,000
- Electricity bill = N3,000
- Water bill = N1,000
- Transportation for delivery = N2,000
- Miscellaneous supplies = N1,500
- Total Expected Expenses = N26,500
Net Financial Position:
- Total Expected Income – Total Expected Expenses = N40,000 – N26,500 = N13,500
In this example, the small bread-making business has a projected monthly surplus of N13,500. This indicates a profitable month, and the entrepreneur can decide how to use this surplus, perhaps by saving it, reinvesting in more ingredients, or expanding production.
0 comments
Open the discussion when you need it. Comments stay collapsed until requested so the initial article remains light.